Should You Switch Your Home Loan?

A New Opportunity for Australian Borrowers

For many Australian homeowners, the past few years have been financially challenging. Rising interest rates increased mortgage repayments, household budgets tightened, and many families had to rethink their spending habits.

Now, the lending landscape is beginning to shift.

Several Australian lenders have started reducing variable home loan rates to attract new customers, creating fresh opportunities for borrowers who may be paying more than they need to.

While lower rates are certainly welcome news, they also raise an important question:

Is it time to review your mortgage?

At MyMoneyMedic, we believe financial wellbeing isn’t just about reacting to market changes—it’s about making informed decisions that support your long-term financial health. Whether you’re a first-home buyer or have been paying off your mortgage for years, understanding your options can help you save money, reduce financial stress, and feel more confident about your future.

Why Are Lenders Cutting Variable Rates?

Competition between lenders is increasing.

As the housing market evolves and borrower demand changes, many banks and financial institutions are lowering selected variable interest rates to encourage customers to refinance or switch lenders.

This competitive environment benefits consumers by providing:

  • More competitive interest rates
  • Cashback or refinancing incentives
  • Flexible loan features
  • Reduced ongoing fees
  • Greater choice when comparing lenders

While not every homeowner will qualify for the lowest advertised rates, increased competition often creates better negotiating power for borrowers.

Why Reviewing Your Mortgage Matters

Many Australians take out a home loan and then rarely review it.

However, your mortgage shouldn’t be a “set and forget” financial product.

Just as people regularly compare insurance policies or utility providers, reviewing your mortgage every few years can potentially deliver significant savings.

Even a small reduction in your interest rate may save thousands of dollars over the life of your loan.

More importantly, lower repayments can improve monthly cash flow, making it easier to:

  • Build savings
  • Reduce financial stress
  • Pay off other debts
  • Invest in future goals
  • Improve overall financial wellbeing

Is Refinancing Right for Everyone?

Refinancing can provide valuable benefits, but it’s not automatically the best choice for every borrower.

Before switching lenders, consider factors such as:

Interest Rate

Compare both the advertised rate and the comparison rate, which includes many fees and charges.

Loan Features

Some loans offer additional benefits such as:

  • Offset accounts
  • Redraw facilities
  • Flexible repayments
  • Extra repayment options

Sometimes these features may be worth slightly higher interest rates if they align with your financial goals.

Refinancing Costs

Switching lenders may involve:

  • Discharge fees
  • Government registration costs
  • Settlement fees
  • Valuation costs

Calculate whether potential savings outweigh these expenses.

Your Long-Term Goals

The lowest rate today isn’t always the best loan tomorrow.

Choose a mortgage that supports your broader financial objectives rather than focusing solely on headline rates.

Don’t Wait for Your Lender to Call You

One common misconception is that lenders automatically reward loyal customers.

Unfortunately, this isn’t always the case.

Many of the most competitive offers are designed to attract new borrowers rather than retain existing ones.

That’s why reviewing your mortgage proactively can be worthwhile.

Even if you don’t change lenders, discussing current market rates with your existing bank may result in a better deal.

Sometimes, simply asking the question can lead to meaningful savings.

Lower Interest Rates Can Improve Financial Wellbeing

Reduced mortgage repayments don’t just improve your bank balance.

They can also improve your quality of life.

Lower financial pressure may provide opportunities to:

  • Increase emergency savings
  • Invest for the future
  • Spend more time with family
  • Reduce financial anxiety
  • Feel more confident managing household finances

At MyMoneyMedic, we believe financial wellbeing extends beyond numbers.

It’s about creating greater peace of mind and giving yourself more choices.

Complete your PulseCheck to understand how your mortgage and household expenses are impacting your overall financial wellbeing.

For practical mortgage guidance and budgeting resources, visit:

ASIC MoneySmart

For official information on Australia’s monetary policy, visit:

Reserve Bank of Australia

When Is a Good Time to Review Your Mortgage?

Financial experts generally recommend reviewing your home loan when:

  • Interest rates change significantly.
  • Your fixed-rate period ends.
  • Your income changes.
  • Your financial goals evolve.
  • You’ve built additional equity.
  • You haven’t reviewed your loan in two years or more.

Regular reviews help ensure your mortgage continues supporting your financial goals rather than limiting them.

Tips: How to Make the Most of Lower Interest Rates

✅ Compare More Than One Lender

Shopping around gives you a clearer understanding of the options available.

✅ Ask Your Current Lender to Match Offers

You may be able to negotiate a lower rate without refinancing.

✅ Use Savings Wisely

If your repayments decrease, consider directing the savings towards:

  • Extra mortgage repayments
  • Emergency savings
  • High-interest debt
  • Long-term investments

✅ Understand All Fees

Always compare the total cost of refinancing—not just the interest rate.

✅ Review Your Budget

A lower mortgage repayment is an excellent opportunity to strengthen your financial position rather than simply increasing discretionary spending.

✅ Monitor Your Financial Wellbeing

Regular financial check-ups help ensure your mortgage continues supporting your long-term goals.

Take Control with the MyMoneyMedic App

A home loan is one of the biggest financial commitments most Australians will ever make.

That’s why understanding your financial wellbeing is just as important as finding a competitive interest rate.

The MyMoneyMedic App helps Australians make smarter financial decisions through practical tools and personalised insights.

With MyMoneyMedic, you can:

✔ Complete your PulseCheck to assess your financial health.

✔ Understand your spending habits.

✔ Identify early signs of financial stress.

✔ Receive personalised financial recommendations.

✔ Access the Care Portal for additional support and wellbeing resources.

Whether you’re refinancing, budgeting, or planning your next financial goal, MyMoneyMedic helps you move forward with clarity and confidence.

📲 Download MyMoneyMedic today
 

Because every great financial decision begins with understanding your financial wellbeing.

Final Thoughts: Small Changes Can Deliver Big Results

A lower interest rate may seem like a small percentage change.

However, over the life of a mortgage, that difference can represent thousands of dollars in savings and significantly reduce financial stress.

The key isn’t simply finding the cheapest loan.

It’s finding the loan that best supports your lifestyle, goals, and long-term financial wellbeing.

By reviewing your mortgage regularly, staying informed about market changes, and understanding your financial position, you’ll be better prepared to make confident decisions—regardless of what interest rates do next.

At MyMoneyMedic, we’re committed to helping Australians build stronger financial futures through clarity, confidence, and practical support.

Watch on YouTube:

18 Lenders Cut Variable Rates to Win New Customers | The Business | ABC News

Why it’s worth watching:

  • Learn why more Australian lenders are reducing variable interest rates.
  • Understand how competition between lenders may benefit homeowners.
  • Discover what refinancing could mean for your monthly repayments.
  • Gain insights into the current Australian home loan market before speaking with your lender.
  • Complement the financial wellbeing tips shared in this article with expert economic commentary.

MyMoneyMedic Tip: After watching the video, take a few minutes to review your own mortgage and household budget. Then complete your PulseCheck in the MyMoneyMedic App to see how your home loan fits into your overall financial wellbeing. Even a small reduction in your interest rate could make a meaningful difference to your long-term financial health.

Mortgage Stress Reaches Critical Levels

Understanding the Pressure Behind the Numbers

For many Australians, owning a home represents more than just a financial asset.

It represents security, stability, and the reward for years of hard work.

However, recent data suggests that mortgage stress is continuing to rise across the country, placing increasing pressure on households already grappling with higher living costs, elevated interest rates, and economic uncertainty.

While headlines can often sound alarming, understanding what mortgage stress actually means—and knowing what actions you can take—can help transform anxiety into confidence.

At MyMoneyMedic, we believe financial wellbeing starts with awareness. The sooner you understand the warning signs, the more opportunities you have to improve your situation and protect your future.

What Is Mortgage Stress?

Mortgage stress occurs when a household spends a significant portion of its income on home loan repayments, leaving less money available for essential living expenses.

While definitions vary, mortgage stress is often associated with households struggling to comfortably meet repayments while maintaining their standard of living.

Importantly, mortgage stress doesn’t necessarily mean someone has missed a payment.

In many cases, it begins much earlier.

Common signs include:

  • Using savings to cover regular bills
  • Increasing reliance on credit cards
  • Reducing discretionary spending dramatically
  • Feeling anxious about future repayments
  • Living from payday to payday
  • Delaying healthcare or important household expenses

These early indicators often provide valuable opportunities to take action before financial pressure becomes overwhelming.

Why Mortgage Stress Is Rising Across Australia

Higher Interest Rates Are Taking Their Toll

Over recent years, many Australians borrowed during a period of historically low interest rates.

As rates increased, monthly repayments rose significantly.

For some homeowners, repayment increases have added hundreds or even thousands of dollars to monthly household expenses.

This sudden shift has reduced financial flexibility and placed greater pressure on family budgets.

For official updates on monetary policy and interest rates, visit the Reserve Bank of Australia.

The Cost-of-Living Challenge

Mortgage repayments are only one part of the financial equation.

Australian households are also facing higher costs for:

  • Groceries
  • Utilities
  • Fuel
  • Insurance
  • Healthcare
  • Education
  • Childcare

When these expenses rise simultaneously, financial buffers can disappear quickly.

Many households that once felt financially secure are now finding it difficult to maintain savings while meeting everyday obligations.

Wage Growth Hasn’t Always Kept Pace

Although incomes have increased in some sectors, wage growth has often struggled to keep pace with rising living expenses.

This creates a situation where households may technically earn more money than before, yet feel financially worse off.

It’s not necessarily about earning less.

It’s about expenses rising faster than income.

The Hidden Impact of Mortgage Stress

Financial Pressure Affects Mental Wellbeing

Money worries rarely stay confined to spreadsheets and bank accounts.

Research consistently shows that financial stress can impact:

  • Mental health
  • Sleep quality
  • Relationships
  • Physical health
  • Workplace performance

At MyMoneyMedic, we recognise that financial wellbeing and overall wellbeing are deeply connected.

That’s why our approach focuses on helping individuals understand both the practical and emotional aspects of financial health.

Decision Fatigue Becomes Real

When households constantly worry about money, decision-making becomes more difficult.

Financial stress can lead to:

  • Avoiding financial conversations
  • Delaying important decisions
  • Ignoring bills or statements
  • Feeling overwhelmed by financial choices

The result is often a cycle where stress creates inaction, and inaction increases stress.

Breaking this cycle begins with gaining clarity about your financial position.

Why Early Action Matters

One of the most important lessons from financial wellbeing research is simple:

The earlier you act, the more options you typically have.

Waiting until financial pressure becomes severe often limits available solutions.

Early intervention may allow homeowners to:

  • Adjust budgets proactively
  • Refinance loans
  • Build emergency savings
  • Reduce unnecessary expenses
  • Seek financial guidance
  • Explore repayment flexibility options

Small changes made today can create significant improvements over time.

Financial Resilience Matters More Than Ever

Economic conditions will continue to change.

Interest rates may rise or fall.

Property markets may strengthen or soften.

Cost-of-living pressures may ease or intensify.

While we can’t control every external factor, we can strengthen our ability to respond.

Financial resilience isn’t about being perfect.

It’s about having enough awareness, flexibility, and preparation to navigate challenges confidently.

This includes:

  • Understanding cash flow
  • Maintaining financial visibility
  • Managing debt responsibly
  • Building emergency savings
  • Creating realistic financial plans

Practical Tips to Reduce Mortgage Stress

Review Your Budget Regularly

Understanding where your money goes each month is one of the most powerful financial habits you can develop.
Even small spending adjustments can create meaningful savings over time.

Build a Financial Buffer

An emergency fund provides protection against unexpected expenses and income disruptions.
Start small and build consistently.

Speak With Your Lender Early

If you’re experiencing financial pressure, contact your lender sooner rather than later.
Many lenders offer support options before serious hardship develops.

Reduce High-Interest Debt

Credit card debt and personal loans often carry higher interest rates than mortgages.
Reducing these debts can improve cash flow significantly.

Focus on Progress, Not Perfection

Financial wellbeing is a journey.
Small improvements made consistently often outperform dramatic changes that are difficult to maintain.

Monitor Your Financial Health

Regular financial check-ins help identify potential issues before they become major challenges.
Awareness creates opportunity.

Take Control with the MyMoneyMedic App

Rising mortgage stress highlights the importance of understanding your financial wellbeing before problems escalate.

The MyMoneyMedic App is designed to help Australians take control of their financial health through practical insights and early intervention.

With MyMoneyMedic, you can:

✔ Complete a PulseCheck to assess your financial wellbeing
✔ Identify early warning signs of financial stress
✔ Access personalised recommendations
✔ Monitor your financial habits and trends
✔ Connect with support through the Care Portal
✔ Build greater financial confidence and resilience

Whether you’re managing a mortgage, navigating rising costs, or simply looking to strengthen your financial future, MyMoneyMedic provides the tools and guidance to help.

📲 Download MyMoneyMedic today:

Because financial wellbeing starts with understanding where you stand.

Stress Is a Signal, Not a Failure

The rise in mortgage stress across Australia is a reminder that many households are facing genuine financial challenges.

But financial pressure should never be viewed as a personal failure.

Economic conditions change.

Life circumstances change.

The important thing is recognising challenges early and taking proactive steps to address them.

With the right information, support, and tools, it’s possible to regain control, reduce financial stress, and build a stronger future.

At MyMoneyMedic, we believe everyone deserves financial clarity, confidence, and wellbeing—regardless of where they are on their financial journey.

And every positive financial outcome begins with a single step forward.

Mortgage Stress Nears 14-Year High

When Homeownership Starts Feeling Heavy

For many Australians, buying a home represents stability, achievement, and long-term security.

Yet for a growing number of households, that dream is becoming increasingly difficult to maintain.

Recent forecasts suggest mortgage stress could soon reach its highest level in more than a decade. Rising interest rates, elevated living costs, and stretched household budgets are creating significant financial pressure for many homeowners.

The reality is that mortgage stress is no longer affecting only those on lower incomes. Increasingly, middle-income families and full-time workers are finding themselves feeling squeezed.

The good news?

Financial stress doesn’t have to become a financial crisis.

At MyMoneyMedic, we believe that awareness, early intervention, and practical action can help households regain control and navigate challenging periods with confidence.

Why Mortgage Stress Is Rising

1. Higher Interest Rates Continue to Impact Households

One of the biggest contributors to rising mortgage stress is the increase in borrowing costs over recent years.

Many homeowners who secured loans during historically low interest rate periods are now facing significantly higher repayments.

For some households, monthly mortgage costs have increased by hundreds—or even thousands—of dollars.

This means less money available for:

  • Savings
  • Everyday expenses
  • Family activities
  • Emergency funds
  • Long-term financial goals

Even households that previously managed comfortably are feeling the pressure.

👉 For official interest rate updates and economic insights, visit Reserve Bank of Australia

2. Cost-of-Living Pressures Are Making It Worse

Mortgage repayments are only one piece of the puzzle.

Australian households are also facing:

  • Rising grocery bills
  • Higher insurance premiums
  • Increased utility costs
  • Fuel price volatility
  • Growing healthcare expenses

When these pressures combine, financial flexibility quickly disappears.

Many families are discovering that even a stable income is no longer providing the same level of comfort it once did.

This is what financial professionals often refer to as “cash flow compression”—where more income is consumed by essential expenses, leaving less room for savings or unexpected costs.

3. Mortgage Stress Often Starts Before Missed Payments

One common misconception is that mortgage stress only occurs when someone falls behind on repayments.

In reality, it often starts much earlier.

Early warning signs include:

  • Regularly dipping into savings
  • Using credit cards to cover essentials
  • Feeling anxious before bills arrive
  • Delaying medical or household expenses
  • Living paycheck to paycheck

These behaviours can indicate that financial resilience is weakening.

Recognising these signals early allows households to take action before pressure escalates.

4. The Hidden Impact on Mental Wellbeing

Financial pressure rarely stays confined to bank accounts.

Research consistently shows that money worries can affect:

  • Sleep quality
  • Mental health
  • Relationships
  • Workplace performance
  • Overall wellbeing

At MyMoneyMedic, we often see financial stress and emotional wellbeing becoming closely connected.

This is why our approach focuses on the whole person—not just the numbers.

Financial health and personal wellbeing go hand in hand.

5. Why Early Action Creates More Options

One of the most important lessons from previous economic cycles is simple:

The earlier you act, the more options you have.

Proactive steps may include:

  • Reviewing your mortgage structure
  • Refinancing opportunities
  • Creating a revised household budget
  • Reducing discretionary spending
  • Seeking professional financial guidance

Small adjustments today can prevent much larger challenges tomorrow.

👉 For practical budgeting tools and calculators, visit ASIC MoneySmart

Tips: How to Reduce Mortgage Stress

✅ Review Your Budget Monthly

Regular budget reviews help identify spending patterns and opportunities for savings.

✅ Build a Financial Buffer

Even small emergency savings can provide valuable protection against unexpected costs.

✅ Speak to Your Lender Early

Many lenders offer hardship assistance or repayment flexibility options before problems escalate.

✅ Prioritise High-Interest Debt

Reducing costly debt can improve monthly cash flow and reduce financial pressure.

✅ Focus on What You Can Control

You can’t control interest rates, but you can control spending habits, budgeting, and financial planning.

✅ Monitor Your Financial Wellbeing

Awareness is one of the most effective tools for preventing financial stress from becoming unmanageable.

Take Control with the MyMoneyMedic App

As mortgage stress rises across Australia, having access to real-time financial insights can make a significant difference.

The MyMoneyMedic App helps Australians better understand, manage, and improve their financial wellbeing through:

PulseCheck – Assess your financial health in minutes

✔ Personalised financial wellbeing insights

✔ Early warning indicators for financial stress

✔ Budgeting and money management tools

✔ Access to the Care Portal for additional wellbeing support

Whether you’re managing a mortgage, planning for the future, or simply trying to stay on top of rising living costs, MyMoneyMedic provides the clarity and support needed to make informed decisions.

📲 Download MyMoneyMedic Today

Because financial wellbeing starts with understanding where you stand.

Final Thoughts: Pressure Doesn’t Have to Become Crisis

The prospect of mortgage stress reaching a 14-year high is a reminder that many Australians are facing genuine financial challenges.

But it’s also a reminder of the importance of preparation.

Economic conditions will change. Interest rates will move. Living costs will fluctuate.

What matters most is how prepared we are to respond.

By staying informed, taking proactive steps, and seeking support when needed, households can build resilience and navigate uncertainty with greater confidence.

At MyMoneyMedic, we’re committed to helping Australians move from financial stress to financial wellbeing—one informed decision at a time.

Why Aussies Are Looking Overseas

Searching for Affordable Opportunities

For many Australians, the dream of owning property is becoming increasingly difficult.

Rising home prices, higher borrowing costs, tighter lending conditions, and ongoing cost-of-living pressure are forcing many people to rethink what financial security looks like.

As a result, some Australians are now looking beyond local borders—particularly toward countries like New Zealand—where property prices in certain areas may appear more affordable.

But while overseas opportunities can sound attractive, they also come with important financial considerations.

At MyMoneyMedic, we believe financial wellbeing starts with clarity, not urgency. Because the goal isn’t simply to buy property—it’s to make decisions that support your long-term financial health.

Why More Australians Are Exploring Overseas Property

1. Housing Affordability Pressures Are Growing

Australia’s housing market has become increasingly challenging for many buyers.

Several factors continue to impact affordability:

  • Higher interest rates
  • Increased deposit requirements
  • Rising construction and insurance costs
  • Strong competition in some markets
  • Slower wage growth compared to living costs

For some Australians, this has created frustration and uncertainty around whether local property ownership remains achievable.

As a result, overseas property markets are attracting attention—especially where homes appear cheaper relative to Australian prices.

2. Why New Zealand Is Drawing Interest

Some Australian buyers are looking at New Zealand due to:

  • Lower property prices in selected regions
  • Lifestyle appeal
  • Geographic proximity
  • Familiar legal and banking systems

However, affordability alone should never drive a major financial decision.

Buying property overseas introduces additional considerations such as:

  • Currency fluctuations
  • Foreign ownership regulations
  • Tax implications
  • Different lending conditions
  • Ongoing management costs

And importantly, “cheaper” doesn’t always mean financially safer.

3. Emotional Decisions Can Create Financial Pressure

When local markets feel difficult, it’s natural to search for alternatives.

However, financial decisions driven by frustration or urgency can increase long-term risk.

Questions to ask before purchasing property anywhere include:

  • Can I comfortably afford ongoing repayments and costs?
  • Do I understand the tax and legal implications?
  • How would changes in interest rates affect me?
  • Am I financially prepared for unexpected expenses?

Strong financial decisions are built on sustainability—not emotion.

👉 For Australian financial education and budgeting support, visit ASIC MoneySmart
https://moneysmart.gov.au

4. Property Is Only One Part of Financial Wellbeing

Owning property can support long-term wealth building—but financial wellbeing is broader than property ownership alone.

True financial stability also includes:

  • Healthy cash flow
  • Manageable debt levels
  • Emergency savings
  • Financial flexibility
  • Mental and emotional wellbeing

At MyMoneyMedic, we often see how financial stress grows when people stretch beyond comfortable limits in pursuit of property goals.

That’s why financial clarity matters more than market hype.

5. Why Financial Awareness Matters Before Big Decisions

Before making a significant purchase—especially across borders—it’s important to fully understand your financial position.

This includes:

  • Your debt-to-income ratio
  • Spending habits
  • Savings resilience
  • Financial stress indicators
  • Long-term affordability

👉 For broader economic and housing updates, visit Reserve Bank of Australia
https://www.rba.gov.au

Tips: How to Approach Property Decisions Wisely

1. Prioritise Affordability Over Emotion

A cheaper property doesn’t automatically mean a better financial outcome.

2. Understand All Ongoing Costs

Factor in taxes, insurance, maintenance, and currency risks.

3. Build a Financial Buffer First

Property ownership becomes less stressful when you have savings flexibility.

4. Avoid Overstretching Your Budget

Sustainable repayments matter more than buying quickly.

5. Research Overseas Rules Carefully

Each country has different lending, tax, and ownership requirements.

6. Use Financial Tools for Clarity

Understanding your finances early helps reduce costly mistakes later.

Take Control with the MyMoneyMedic App

Big financial decisions deserve clear financial insight.

The MyMoneyMedic App helps Australians understand and improve their financial wellbeing through:

PulseCheck – Instant financial health analysis
✔ Smart budgeting and spending insights
✔ Early financial stress detection
✔ Personalised financial recommendations
✔ Access to the Care Portal for additional wellbeing support

Whether you’re buying locally, investing, or planning for the future, clarity creates confidence.

📲 Download MyMoneyMedic today:

Final Thoughts: Financial Confidence Starts With Clarity

Property opportunities may exist both locally and overseas—but financial wellbeing should always remain the priority.

The right property decision is not the one that feels exciting in the moment.

It’s the one that supports your long-term stability, flexibility, and peace of mind.

At MyMoneyMedic, we believe informed decisions create stronger futures. And no matter where you’re looking to invest or buy, financial awareness will always be one of your greatest assets.

What the 2026 Budget Means for You

Turning Budget Headlines Into Financial Clarity

Every Federal Budget brings a wave of headlines, promises, and economic forecasts.

But for most Australians, the real question is much simpler:

“What does this actually mean for me and my household?”

The 2026 Federal Budget focuses heavily on easing cost-of-living pressure, supporting households, and strengthening the broader economy. From tax relief measures to energy support and housing initiatives, the goal is to provide some breathing room during a financially challenging period.

At MyMoneyMedic, we believe understanding these changes clearly can help reduce stress and improve decision-making. Because financial wellbeing starts with knowing how national changes affect your personal finances.

Body: Breaking Down the 2026 Federal Budget

1. Cost-of-Living Relief Remains a Key Focus

One of the biggest themes in this year’s budget is ongoing cost-of-living support.

Many Australians continue to feel pressure from:

  • Higher grocery prices
  • Energy bill increases
  • Mortgage and rental stress
  • Insurance and healthcare costs
  • Slower wage growth compared to inflation

To address this, the government has introduced or expanded support measures designed to ease financial pressure for households.

While support may not eliminate rising costs entirely, it aims to create some relief and stability during ongoing economic uncertainty.

or official budget information, visit Australian Federal Budget

2. Tax Relief and Household Support

The budget includes adjustments aimed at improving household cash flow through:

  • Tax changes
  • Energy bill assistance
  • Increased support payments for eligible Australians
  • Healthcare and pharmaceutical funding

For many families, these measures may help offset some of the financial strain caused by inflation and higher living expenses.

However, it’s important to remember:
Short-term relief works best when combined with strong personal financial habits.

3. Housing and Affordability Remain Front and Centre

Housing affordability continues to be one of Australia’s biggest financial challenges.

The budget includes measures aimed at:

  • Increasing housing supply
  • Supporting first-home buyers
  • Encouraging new housing development
  • Improving rental market conditions

While these initiatives may take time to flow through the market, they highlight a growing recognition that housing pressure impacts overall financial wellbeing.

 For housing market and economic updates, visit Reserve Bank of Australia
 

4. Why Personal Financial Planning Still Matters Most

Government support can help ease pressure—but long-term financial wellbeing still depends on personal financial awareness and preparation.

That means:

  • Understanding your spending habits
  • Managing debt carefully
  • Building a financial buffer where possible
  • Planning for future economic changes

Economic conditions will continue to shift over time.

The stronger your financial foundation is, the more resilient you become during those changes.

5. Turning Economic Changes Into Opportunity

Budgets often focus heavily on numbers and policy—but behind every policy is a real household trying to navigate everyday financial decisions.

Periods of economic change can also become moments to:

  • Reassess financial goals
  • Improve money habits
  • Reduce unnecessary debt
  • Create stronger long-term plans

And importantly, small changes today often create significant financial benefits over time.

Internal Link Suggestion: Use MMM’s PulseCheck tool to assess your financial health and identify opportunities to improve your financial wellbeing (insert internal MMM link)

For practical budgeting guidance, visit ASIC MoneySmart

Tips: How to Respond to Budget Changes Wisely

1. Review Your Household Budget

Understand how rising costs are impacting your monthly cash flow.

2. Don’t Rely Solely on Government Relief

Support measures help—but long-term financial resilience comes from preparation and good habits.

3. Prioritise Building a Financial Buffer

Even small savings create flexibility and reduce stress.

4. Reassess Debt and Repayments

Higher rates and living costs make debt management more important than ever.

5. Focus on Long-Term Financial Health

Short-term economic conditions will change. Strong financial habits provide stability over time.

6. Use Financial Tools That Create Clarity

Real-time awareness helps you make better decisions before pressure escalates.

Take Control with the MyMoneyMedic App

Financial wellbeing isn’t just about surviving economic changes—it’s about understanding them and responding with confidence.

The MyMoneyMedic App helps Australians stay financially aware through:

PulseCheck – Instant financial health insights
Smart budgeting visibility
Personalised recommendations
Early financial stress detection
Access to the Care Portal for broader wellbeing support

Because financial clarity creates better decisions—and better decisions create stronger futures.

 Download MyMoneyMedic today:


Final Thoughts: Financial Clarity Creates Confidence

The Federal Budget affects everyone differently.

For some households, it may provide temporary relief. For others, it may simply reinforce the importance of stronger financial planning moving forward.

But one thing remains true:

The more awareness you have around your finances, the more control you gain over your future.

At MyMoneyMedic, we’re here to help Australians navigate financial change with clarity, confidence, and practical support—because financial wellbeing should feel empowering, not overwhelming.

When Property FOMO Starts Fading

From FOMO to Financial Caution

For years, Australia’s property market was driven by one powerful emotion:

FOMO — Fear of Missing Out.

Buyers rushed into the market worried that if they waited too long, prices would rise beyond reach forever.

But now, sentiment appears to be shifting.

As affordability pressures rise, borrowing becomes harder, and economic uncertainty grows, many Australians are moving from “fear of missing out” to something very different:

FOOP — Fear of Overpaying.

And honestly, that shift may not be a bad thing.

At MyMoneyMedic, we believe financial wellbeing starts with clarity—not pressure. Because the best financial decisions are usually made calmly, not emotionally.

Body: Why Property Sentiment Is Changing

1. The End of the “Buy at Any Cost” Mentality

During the property boom, many buyers felt intense urgency.

Low interest rates, rising prices, and competition pushed people to:

  • Stretch borrowing limits
  • Waive due diligence
  • Rush financial decisions
  • Prioritise speed over long-term affordability

Now, conditions are changing.

Higher interest rates and slower market momentum are encouraging buyers to pause, reassess, and think more strategically.

This shift from emotional urgency to financial caution reflects a market becoming more balanced.

2. Why FOOP Is Growing

The “fear of overpaying” is increasing because many buyers are questioning whether property prices can continue rising at the same pace.

Several factors are contributing to this:

  • Reduced borrowing power due to higher rates
  • Rising mortgage stress among households
  • Slower economic growth
  • Higher living costs impacting savings capacity
  • Greater uncertainty about future property values

As a result, buyers are becoming more selective—and less willing to chase inflated prices.

And that can actually create healthier decision-making.

For broader economic updates, visit Reserve Bank of Australia

3. Why Emotional Buying Can Be Risky

Property decisions are emotional by nature.

However, making major financial decisions based on fear often creates unnecessary risk.

FOMO can lead to:

  • Overextending financially
  • Taking on unmanageable debt
  • Ignoring long-term affordability
  • Increased financial stress later

Now that the market is slowing, buyers have an opportunity to focus on:

  • Financial sustainability
  • Smart budgeting
  • Long-term planning
  • Better negotiation opportunities

And that’s a positive shift.

4. Slower Markets Can Create Better Opportunities

A cooling market doesn’t always mean bad outcomes.

In many cases, it creates:

  • More time to research
  • Reduced competition
  • Greater negotiation power
  • Better decision-making conditions

This allows buyers to focus on what truly matters:

Can I comfortably afford this property long-term?

That question matters far more than whether prices rise or fall next month.

5. Financial Wellbeing Matters More Than Market Hype

At MyMoneyMedic, we believe your personal financial position matters more than market headlines.

Whether the market rises, cools, or stabilises, the goal remains the same:

  • Protect your financial wellbeing
  • Reduce unnecessary stress
  • Build long-term resilience

Internal Link Suggestion: Use MMM’s PulseCheck tool to understand your financial readiness before making property decisions (insert internal MMM link)

For practical budgeting and financial education, visit ASIC MoneySmart

Tips: How to Navigate a Cooling Property Market

1. Focus on Affordability First

Don’t buy based on market hype—buy based on sustainable repayments.

2. Avoid Emotional Pressure

Slower markets give you time. Use it wisely.

3. Build a Financial Buffer

Unexpected expenses and rate changes happen. Preparation creates flexibility.

4. Stress-Test Your Budget

Could you still manage repayments if costs increased further?

5. Research Thoroughly

Take advantage of reduced urgency to compare suburbs, loans, and opportunities carefully.

6. Prioritise Financial Clarity

Understanding your full financial picture reduces risk and improves confidence.

Take Control with the MyMoneyMedic App

Property decisions are some of the biggest financial commitments people make.

The MyMoneyMedic App helps you make those decisions with greater confidence and clarity.

Inside the app, you can:

Complete your PulseCheck for real-time financial insights
Track spending and debt patterns
Receive personalised financial guidance
Identify financial stress risks early
Access support through the Care Portal

This isn’t just about buying property.

It’s about protecting your financial wellbeing while building your future.

Download MyMoneyMedic today:

Final Thoughts: Calm Decisions Create Stronger Outcomes

Markets change.

Sentiment changes.

But strong financial decisions are built on the same foundation:
clarity, preparation, and long-term thinking.

The shift from FOMO to FOOP may actually help Australians make healthier property decisions moving forward.

And that’s a good thing.

At MyMoneyMedic, we’re here to help you navigate uncertainty with confidence—so you can focus less on fear, and more on financial wellbeing.

Mortgage Stress Is Rising Fast

Working Hard Isn’t Always Enough Anymore

For many Australians, owning a home was meant to represent stability, security, and progress.

But today, even full-time workers are finding themselves under growing financial pressure as rising interest rates continue to push mortgage repayments higher.

The reality is confronting:
People who once felt financially comfortable are now experiencing mortgage stress—not because they failed financially, but because economic conditions have changed rapidly.

At MyMoneyMedic, we believe financial wellbeing starts with understanding. Because when pressure rises, clarity becomes one of the most important tools you can have.

Why Mortgage Stress Is Increasing

1. The Impact of Higher Interest Rates

Interest rate rises have significantly increased mortgage repayments across Australia. For households already balancing rising living costs, the impact has become difficult to ignore.

According to recent reports, thousands of Australians—including full-time workers—are now being pushed into mortgage stress as repayments consume a larger share of household income.

For many families, this means:

  • Less disposable income
  • Reduced savings capacity
  • Greater reliance on credit
  • Increased financial anxiety

And importantly, this pressure is happening while the cost of everyday essentials continues to rise.

👉 For official interest rate updates and economic insights, visit Reserve Bank of Australia

2. Mortgage Stress Doesn’t Always Look Obvious

Mortgage stress isn’t only about missing repayments.

Often, it starts much earlier.

Some of the early warning signs include:

  • Constantly checking account balances before bills arrive
  • Using savings to cover regular expenses
  • Relying more heavily on credit cards
  • Feeling anxious about future repayments
  • Delaying medical, personal, or lifestyle expenses

Many people experiencing financial pressure still appear financially stable on the surface.

That’s why awareness matters.

3. Why Full-Time Workers Are Feeling the Pressure

Historically, stable employment offered financial security.

However, today’s environment is different.

Even with full-time income, households are facing:

  • Higher mortgage costs
  • Increased insurance premiums
  • Rising grocery and utility expenses
  • Childcare and education pressures
  • Slower wage growth compared to inflation

This creates a situation where income is still coming in—but financial breathing room continues shrinking.

And when households lose flexibility, stress rises quickly.

4. The Emotional Toll of Financial Pressure

Mortgage stress affects more than money.

It impacts:

  • Mental wellbeing
  • Relationships
  • Sleep quality
  • Confidence and decision-making

At MyMoneyMedic, we often talk about the Compounding Cycle:

Rising costs
→ Financial stress
→ Mental strain
→ Reduced decision-making capacity
→ Greater financial pressure

Breaking this cycle early can protect both your finances and your overall wellbeing.

👉 Use MMM’s PulseCheck tool to understand your current financial health and identify pressure points early 

👉 For budgeting guidance and financial education, visit ASIC MoneySmart

5. Why Early Action Matters

One of the biggest financial mistakes people make during difficult periods is waiting too long to act.

The earlier you address pressure, the more options you usually have.

This might include:

  • Refinancing your loan
  • Adjusting spending habits
  • Consolidating debt
  • Speaking to financial professionals
  • Creating a clearer financial plan

Small adjustments made early often prevent much larger problems later.

And importantly, asking for support is not weakness—it’s smart financial management.

Tips: How to Reduce Mortgage Stress

✅ 1. Review Your Loan Structure

Speak with your lender or broker about refinancing or repayment flexibility options.

✅ 2. Rework Your Household Budget

Focus on separating essential spending from discretionary spending.

✅ 3. Build Even a Small Financial Buffer

Small savings create stability and reduce reliance on debt during emergencies.

✅ 4. Prioritise High-Interest Debt

Reducing expensive debt can improve monthly cash flow quickly.

✅ 5. Avoid Financial Avoidance

Checking your finances regularly—even when uncomfortable—creates awareness and control.

✅ 6. Use Technology to Stay Ahead

Financial tracking tools help identify risks before they become overwhelming.

Take Control with the MyMoneyMedic App

When financial pressure increases, clarity becomes essential.

The MyMoneyMedic App helps Australians better understand and manage their financial wellbeing through:

PulseCheck – Instant financial health insights
✔ Real-time tracking and personalised recommendations
✔ Early identification of financial stress risks
✔ Access to the Care Portal for broader wellbeing support
✔ Practical tools designed to build long-term resilience

This isn’t just about budgeting.

It’s about helping people feel confident, informed, and supported through difficult financial periods.

📲 Download MyMoneyMedic today:

Final Thoughts: Financial Pressure Can Be Managed

Mortgage stress is becoming more common—but it doesn’t have to define your future.

The most important step is recognising pressure early and taking action before it escalates.

Even during difficult economic periods, small changes can create meaningful improvements over time.

At MyMoneyMedic, we believe financial wellbeing is built through awareness, support, and practical action—not perfection.

And no matter where you’re starting from today, there are always steps forward.

Australians Facing Financial Stress

A Wake-Up Call for Financial Wellbeing

Recent reporting by SBS News highlights a concerning milestone: more Australians are experiencing serious financial hardship than ever before. From mortgage strain to rising utility bills and credit stress, households across the country are feeling the weight of ongoing cost pressures.

While this news may feel unsettling, it also serves as an important reminder — financial resilience matters more than ever. At MyMoneyMedic (MMM), we believe clarity creates calm. When you understand what’s happening, you can take steady, confident action.

📊 What’s Behind the Rising Financial Pressure?

Several economic factors are contributing to the current stress levels:

🏦 1. Higher Interest Rates

The Reserve Bank of Australia has increased interest rates in recent years to manage inflation. While necessary for long-term economic stability, higher rates mean increased mortgage repayments and loan costs for many households.

🛒 2. Cost-of-Living Increases

Data from the Australian Bureau of Statistics shows that essentials such as groceries, energy, insurance, and rent have risen significantly. Even small increases across multiple categories can stretch budgets.

💳 3. Growing Debt Pressures

Some households are turning to credit cards or buy-now-pay-later services to bridge gaps, which can compound financial stress if not managed carefully.

👥 4. Income Not Keeping Pace

Although wage growth has improved in certain sectors, many Australians still feel their income isn’t rising fast enough to offset living expenses.

Importantly, these challenges are structural — not personal failures. Understanding that reduces unnecessary self-blame and encourages proactive planning.

🌱 The Positive Perspective: You Can Strengthen Your Position

Economic cycles rise and fall. However, personal financial clarity provides stability during uncertainty.

Here’s what remains within your control:

  • How you budget
  • How you prioritise expenses
  • How you build savings
  • How you manage debt
  • How you increase income potential

Even small, consistent adjustments can dramatically improve long-term financial wellbeing.

💡 Practical Tips to Reduce Financial Stress

✅ 1. Review Essential Expenses First

Start with housing, utilities, transport, and insurance. Negotiating providers or switching plans may free up extra cash.

✅ 2. Create a Clear Spending Plan

Allocate income intentionally. A zero-based budget ensures every dollar has a purpose.

✅ 3. Build a Starter Emergency Fund

Even $1,000 set aside can reduce anxiety during unexpected expenses.

✅ 4. Prioritise High-Interest Debt

Focus on clearing credit cards or short-term debt first to minimise compounding costs.

✅ 5. Seek Support Early

If repayments feel overwhelming, contact lenders early. Many hardship programs exist — and early communication often leads to better outcomes.

🎥 Why Australians are falling behind | The Business | ABC NEWS

For a deeper understanding of Australia’s financial stress trends and economic outlook:

📱 Take Control with the MyMoneyMedic App

When financial stress rises nationally, personal clarity becomes even more important.

The MyMoneyMedic App helps you:

  • Track spending automatically
  • Identify budget leaks
  • Set achievable savings goals
  • Monitor debt repayment progress
  • Build confidence through clear insights

Instead of reacting to financial pressure, take calm and proactive control.

👉 Download MyMoneyMedic today on Google Play or the Apple App Store and start building financial resilience with clarity and hope.

We’re still improving the app & would love your feedback. Share your thoughts with us here:

📝 Submit your feedback

🌟 Final Thoughts: Resilience Is Built Step by Step

Yes, financial hardship statistics are rising. But numbers don’t define your future.

With awareness, structured planning, and consistent habits, you can strengthen your financial foundation — even in challenging times.

Remember:

  • Small improvements compound.
  • Knowledge reduces fear.
  • Action builds confidence.

At MyMoneyMedic, we’re here to help you move forward — with hope, clarity, and positivity.

The Australian Dream or the Australian Scheme?

When someone sits across from us at MyMoneyMedic drowning in mortgage stress, we see a pattern that repeats too often to be random.

It’s not one dramatic moment. It’s a sequence.

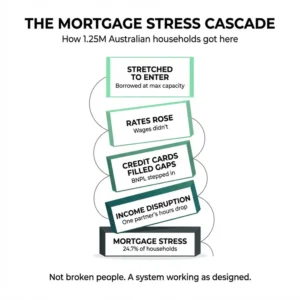
They stretched to enter the market because everyone said “get in now or you’ll be locked out forever.” They borrowed at the top of their capacity because property “always goes up.” Then rates rose. Costs rose. Wages didn’t.

Credit cards filled the gaps. Buy Now Pay Later stepped in. Tax debt lingered. The mortgage remained untouchable.

By the time they reach out for help, they’re emotionally exhausted. And they blame themselves.

That’s the moment we know the system isn’t broken. It’s working exactly as designed.

The System Produces the Outcome It Was Built For

Banks profit from larger loans over longer terms. Property demand benefits from urgency and FOMO. Household debt fuels economic growth.

When families are leveraged to the edge, stressed, and dependent on continued growth to stay afloat, that isn’t an accident. It’s an outcome.

As of November 2025, 24.7% of Australian mortgage holders are classified as “At Risk” of mortgage stress. That’s 1.25 million households where mortgage repayments consume a dangerous portion of income, leaving minimal buffer for life’s inevitable disruptions.

The dream only works if nothing goes wrong for 30 years.

Life doesn’t work like that.

Normal Life Exposes Maximum Leverage

The most common trigger we see isn’t dramatic. It’s income disruption.

One partner goes on parental leave. One income drops due to job change or redundancy. A small business owner has three slow months.

That’s it.

Suddenly, a household that “qualified comfortably” can’t breathe.

Most families don’t borrow based on surplus. They borrow based on maximum serviceability. Two full incomes assumed. Minimal lifestyle change assumed. Rate buffers that feel theoretical until they aren’t.

When one income softens, the margin disappears.

The mortgage was manageable as long as both engines were running perfectly. That’s the fragility.

Roy Morgan’s research confirms that unemployment has the largest impact on income and mortgage stress. Yet affordability assessments assume two full-time incomes remain stable indefinitely.

Among lower socio-economic groups, full-time employment among mortgage holders fell by 11.6% year-over-year. Employment assumptions collapse quickly for vulnerable households.

The Banking Assessment Disconnect

Here’s the uncomfortable truth about affordability assessments.

Most people hear: “You can afford this mortgage.”

Banks are calculating something different.

Income is treated as fixed and ongoing

Banks look at your current declared income and assume it keeps flowing, unchanged, forever. Full-time salary? Assumed stable. Bonus or overtime? Partially counted. Side gigs? Sometimes ignored.

Reality: Income isn’t guaranteed. Promotions stall. Hours get cut. Businesses fluctuate. Parental leave happens.

Expenses are treated as generic or minimal

Banks use broad expense categories, not your actual spending. They assume a “basic lifestyle” number for groceries, utilities, insurance. Car loans, childcare, school fees, subscriptions? Factored in minimally or ignored.

Reality: Day-to-day living costs are higher than these benchmarks and add up quickly.

Stress tests are theoretical

Banks might add a 2-3% buffer for interest rate increases. But it’s applied to the mortgage only, not your total household cashflow. It assumes you adjust perfectly without real-life friction.

Reality: Small rate rises plus normal life expenses equals immediate pressure, not a buffer.

Australian banks routinely approve loans at 5-7 times annual income. The average home loan debt is now $327,514 according to NAB’s 2024 data, while average household gross disposable income was only $139,064.

Debt is growing twice as fast as income.

No human psychology is accounted for

Banks calculate numbers. They don’t account for financial stress impacting decisions, emotional spending, or risk tolerance.

Reality: Even when clients can technically make payments, the mental load is crushing. Sleep, focus, relationships all suffer.

The formula answers: “Could this borrower service a loan under ideal conditions?”

Not: “Can this household live, save, and respond to life while paying this mortgage?”

That gap is exactly where stress builds.

The Tax Incentive Amplifier

Negative gearing by property investors reduced personal income tax revenue by $10.9 billion in the 2023-24 financial year. That’s up from $6.7 billion in 2014-15.

That’s $10.9 billion in foregone revenue effectively subsidizing property speculation while first-home buyers compete against tax-advantaged investors.

In 2022-23, about 1.1 million Australians were negatively geared. That’s 49.4% of all property investors gambling on capital gains to offset years of losses.

The Reserve Bank of Australia stated in 2003 that resources and finance are being disproportionately channeled into property investment, with tax effectiveness being an important selling point used by property promoters.

Tax policy, not housing need, is driving investment behavior.

Research by the Australian Housing and Urban Research Institute reveals that most negatively geared investors buy existing dwellings rather than building new homes. The policy inflates prices for existing stock without meaningfully increasing housing supply.

It’s a demand accelerator disguised as a supply solution.

The 5% Deposit Scheme: Solution or Accelerant?

From October 1, 2025, the Australian Government 5% Deposit Scheme was expanded with no income caps, no waitlists, and higher property price caps up to $1.5 million in parts of NSW.

First-home buyers can now enter the market with minimal equity and maximum exposure to rate fluctuations and life disruptions.

The scheme removes Lenders Mortgage Insurance but requires the property to remain owner-occupied with principal and interest repayments for up to 30 years.

If borrowers fail to meet ongoing obligations like losing a job or needing to relocate, the guarantee may no longer apply. They could face paying LMI or additional costs at their most vulnerable moment.

Parliamentary Budget Office modeling shows the scheme is highly sensitive to assumptions around interest rates, house price growth, and default rates. Default rates are projected at 0.3% annually.

This assumes ideal conditions over 30 years. The exact fragility pattern we see collapsing when normal life happens.

The Household Debt Reality

Australian household debt reached a record $3.33 trillion in June 2025. That’s a 6% increase in just one year.

The average Australian household now carries $313,633 in total debt, with mortgage debt alone representing 135% of household disposable income.

Australia has the fifth-highest household debt-to-income ratio among OECD countries at 211%. The average household owes more than twice what it earns annually.

We’re borrowing two years of income to fund our lifestyle and housing.

The debt-to-income ratio hit 182% in Q4 2024, tracking near record highs. This wasn’t an accident. It’s the predictable outcome when banks approve loans at maximum serviceability and tax policies incentivize speculation over genuine housing needs.

The Stress Distribution Problem

Mortgage stress hasn’t eased evenly.

While higher-income households have found relief, stress has actually increased among the lowest two socio-economic quintiles by over 5% year-over-year.

Relief from rate cuts is bypassing the 40% of Australians who need it most.

Even as interest rates dropped, mortgage stress surged in June 2025 to 28.4%. The highest since January 2025.

Why? Because households were borrowing larger amounts, chasing rising property prices with their newfound “affordability.”

The system encourages maximum leverage the moment conditions slightly improve.

Median mortgage repayments peaked at 47.1% of median household income in September 2024 before dropping to 45% by September 2025. Still far above the traditional 30% mortgage stress threshold.

Nearly half of household income consumed by housing before accounting for food, transport, childcare, or savings.

Why People Don’t Stress-Test

It’s not because people are careless.

Optimism bias: We naturally assume the future will resemble the present. Two stable incomes today feel permanent.

Social proof: Everyone else is borrowing big. If your peers are stretching, stretching feels normal.

Lending framework psychology: When a bank says you can borrow $1.2M, most people hear “you can afford $1.2M.” They don’t hear “you can survive $1.2M under ideal assumptions.”

No one models the downside in real terms: Very few borrowers sit down and calculate what happens if one income drops 30%, rates rise another 1-2%, or they need $20k unexpectedly.

They’re shown approval capacity, not fragility thresholds.

The Independent Advice Vacuum

Access to unbiased financial wellness guidance is rare.

Most advice comes from parties with skin in the game. Mortgage brokers earn commissions on loan size. Real estate agents benefit from higher prices. Bank employees have lending targets.

Financial literacy is rarely taught early or practically.

When families need independent perspective on whether they should stretch for that property, where to find it?

The gap between what’s approved and what’s sustainable requires someone to map both scenarios clearly, calmly, without judgment.

At MyMoneyMedic, we map the official bank-approved scenario and the real-life cashflow scenario.

Once clients see the divergence, decisions change. Borrowing less. Building buffers. Planning strategically rather than hoping for ideal assumptions.

The Generational Impact

Today’s policies are mortgaging future generations’ financial and mental wellbeing.

Young Australians entering the market face a choice: stretch beyond comfort or watch homeownership slip away.

The Australian dream has become a 30-year bet that nothing will go wrong.

Babies. Career shifts. Business cycles. Aging parents. School fees. Burnout.

Life transitions are predictable. But our borrowing decisions assume stability.

The problem isn’t ambition. It’s building a 30-year commitment on a 12-month snapshot.

The Path Forward: Clarity Over Leverage

We don’t sit across from people and tell them the system is rigged.

We sit with them and say: “You’re not bad with money. You’re in a high-pressure structure without visibility.”

When we map their numbers clearly, something powerful happens.

They see where the pressure truly sits. They understand their risk exposure. They regain agency.

Once there’s clarity, there’s choice.

The real Australian Dream isn’t just owning a house.

It’s sleeping at night. Not fearing every rate rise. Having buffers. Having options. Feeling in control.

Home ownership can absolutely be part of that dream. But only if it’s aligned with cashflow reality, not social expectation.

What We Believe

The system won’t change overnight.

But individuals can change how they engage with it.

That’s where power comes back.

When someone realizes they’re not broken, that they’ve simply been operating inside a system that rewards maximum leverage, everything shifts.

Not into fear. Into strategy.

When clients stress-test properly, they borrow differently. They build buffers first. They think in cashflow, not just asset value. They prioritize flexibility.

The dream isn’t fragile if it’s built with margin.

At MyMoneyMedic, we’re building a holistic finance health and wellbeing ecosystem to democratize financial wellness solutions. We’re not just another financial advisor.

We’re financial stress specialists focused on data privacy, trust, and care.

Because the real crisis isn’t just about property prices.

It’s about the mental, physical, and emotional toll of carrying debt that looks affordable on paper but crushes people in reality.

And when we help someone see their numbers clearly, map their actual risk, and build a plan with breathing room, that’s when the Australian dream becomes possible again.

Not as a scheme. As a choice.